
Occupational pensions: tax treatment and tax advantages
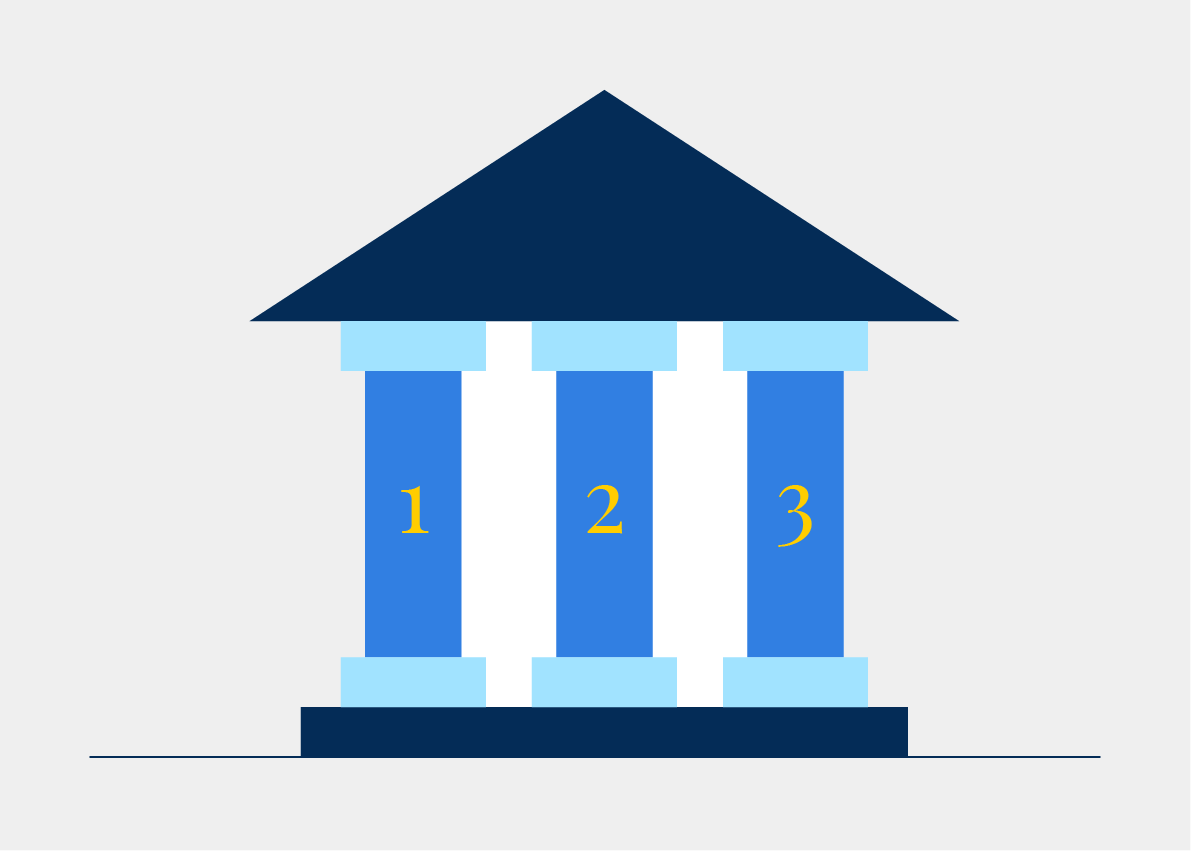
Occupational pension provision (BVG/LPP) is the 2nd pillar of the Swiss pension system, alongside the 1st pillar (AHV/AVS and IV/AI) and the 3rd pillar (individual pension provision). It is based on the employment relationship between employees and companies and is therefore described as “occupational”. In this article we will examine the tax treatment of BVG/LPP contributions and the tax advantages available to employers and employees.
Legal foundations of occupational pension provision
Employers who employ staff in their company who are subject to compulsory BVG/LPP insurance are required by law to join a pension institution entered in the register for occupational pension provision in Switzerland, and to insure their employees.
An employer may join several pension institutions, depending on the structure of its workforce and on the structure the company wishes to give its occupational pension provision.
Tax conditions for pension institutions
The Occupational Pensions Act (BVG/LPP) stipulates that pension institutions under private or public law with legal personality are exempt from:
- direct federal taxes
- cantonal and municipal taxes
- cantonal and municipal inheritance and gift taxes
To the extent that their income and assets are used exclusively for occupational pension provision. (Art. 80 BVG/LPP)
Tax treatment of ordinary BVG/LPP contributions
The employer’s obligation to join a recognised pension institution means that it must pay 100% of the contributions to the institution, both its own share and the share of its employees. It then deducts each employee’s share from their pay.
The tax treatment of these charges, under Art. 80 et seq. BVG/LPP, allows pension contributions to be deducted. The employer includes its share of the contributions paid to the pension institution in its staff costs, while the employee has the charges deducted from their pay, so they are not taken into account when calculating their taxable income, as they are tax-deductible.
It follows that all contributions paid to a pension institution are tax-exempt.
Voluntary contributions (buy-ins) to occupational pension provision
Voluntary buy-ins are additional capital payments that an employee affiliated to a pension institution can make into their pension account to close any gaps or simply to improve their future pension.
Main benefits
- Full deductibility: the amount paid can be deducted in full from taxable income, thereby reducing the tax burden in the year in which the buy-in is made.
- Closing any “pension gaps”, which naturally arise during one’s working life.
- Higher retirement benefits: it increases the accumulated capital and, consequently, the future pension.
Tip: before making a buy-in, it is necessary to check the limits, the pension institution’s regulations and any restrictions (such as waiting periods before the capital can be withdrawn).
Employer contribution reserves for BVG/LPP
For greater flexibility, greater financial stability or for planning purposes (…), the employer can set aside a contribution reserve (known as the employer contribution reserve). In this way, future 2nd pillar charges that will have to be paid to the pension institution are set aside in advance. This mechanism allows the company, for example, to be exempted from paying contributions in years of financial contraction, or to be able to count on greater resources for planned investments without having to worry about financing the BVG/LPP. In these two “example scenarios”, 2nd pillar benefits would be financed through the dedicated reserve, effectively relieving the company’s accounts in certain years.
The employer contribution reserve is also tax-exempt. This aspect is certainly decisive from a planning perspective (…).
Close attention must be paid to the tax provisions laid down by the Confederation and the company’s canton of domicile for this particular pension contribution.
Extra-mandatory pension plans and supplementary plans
The law sets minimum parameters for occupational pension provision. However, pension institutions are free to offer benefits above the legal minimums. These benefits can be found in pension plan formulations known as:
- Extra-mandatory plans: which offer insurance and contribution guarantees above the minimum parameters set by law.
- Supplementary plans, which are added to the basic, or primary, plan and allow the insured person to secure additional benefits.
These supplementary forms are driven by the need to obtain the best possible cover and adequately protect employees’ pension provision. It is up to the employer to assess these choices.
Tax advantages for employees
From a tax perspective, these instruments offer significant advantages:
- higher contributions to one’s own pension provision (deducted from income),
- a larger gap that can be closed through voluntary buy-ins, maximising tax deductions.
Wealth tax exemption for pension assets
A detail that is by no means insignificant, but which is often overlooked, is the wealth tax exemption for pension assets. Like the contributions paid, employees’ personal assets held by pension institutions are also tax-exempt.
This applies both to assets in the 2nd pillar and to those in the 3rd pillar.
Taxation of 2nd pillar benefits
Once the time comes to access one’s retirement assets, the taxation of the savings needs to be considered.
In the 2nd pillar there are two ways of drawing the assets: pension and lump sum.
Drawing BVG/LPP capital as a pension
For tax purposes, drawing a pension is treated exactly like income from gainful employment; it will therefore be subject to income tax, after any deductions. In this case the assets remain with the pension institution and will not be subject to wealth tax.
Drawing BVG/LPP capital as a lump sum
When the capital is drawn as a lump sum, it is subject to one-off taxation, separate from other income, at a preferential rate. Once the capital has been paid out, the amount becomes part of one’s personal assets and is subject to wealth tax in subsequent years.
Conclusions
The Swiss pension system, and the 2nd pillar in particular, offer clear and concrete instruments that benefit from extremely favourable tax levers. Every step in this field must be accompanied by in-depth knowledge of the subject and by expert analysis.
The cantonal tax authorities closely monitor how buy-ins and reserves are handled. Transactions that are not in line with the law or with cantonal practice may be challenged, with possible claims for additional tax or penalties.
Specialist advice with Assidu
Pension planning is a complex process that requires specific legal, tax and insurance expertise. Assidu provides advice of the highest quality and excellence, with high standards of assurance, offering:
- A team of experts: Assidu provides specialists who work with advanced analysis tools to guarantee personalised solutions that comply with current regulations.
- Step-by-step support: from choosing the pension institution to defining extra-mandatory or supplementary plans, managing voluntary buy-ins and providing support on the delicate tax issues associated with these particular transactions.
Article written by:
Maurizio Reichlin
Insurance Expert with Federal Diploma*Assidu Individual Life contact person for Ticino*